by Alison Jobson | Aug 6, 2026
Client: Local small business
Facility: £493,500 commercial mortgage
Purpose: Farm purchase
Client background
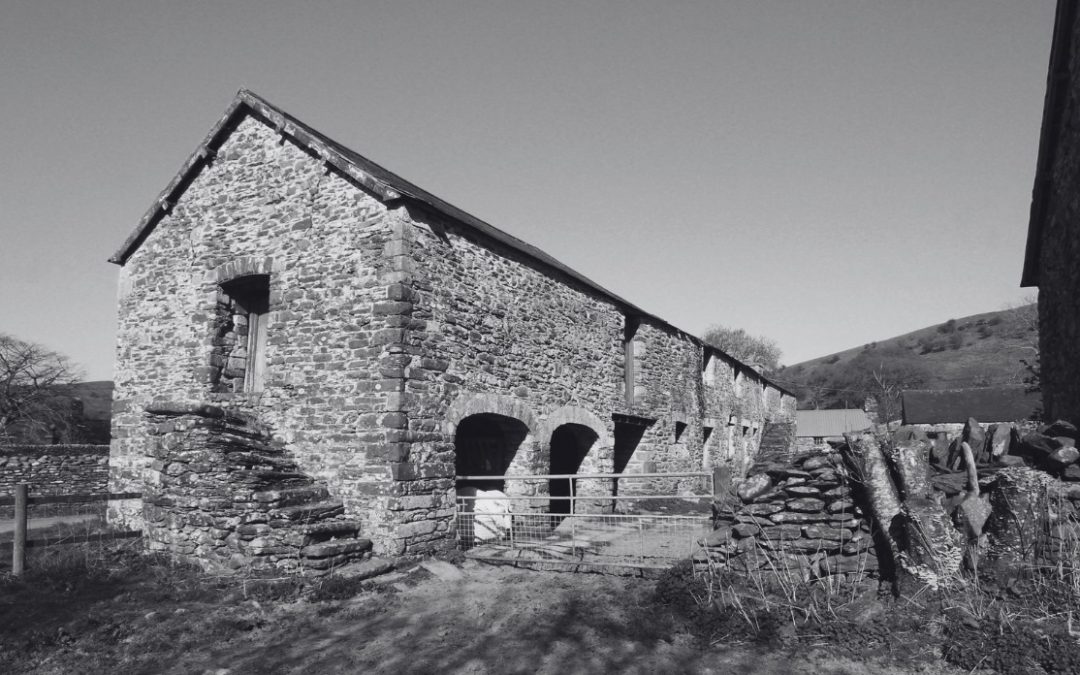
Our client, a local company that had been trading for about ten years, wanted to buy a 15-acre farm in the Peak District to run the business from. The owner planned to live on the farm with his family and use the move to diversify the business into several new ventures.
His plans included adding a caravan and motorhome micro-site, native-breed beef cattle for local wholesale and direct box sales, seasoned hardwood sales, tree surgery, agricultural contracting including groundworks and drainage, and DIY livery for people bringing their horse on holiday, alongside office and workshop space for the existing business.
Challenge
Finance was hard to secure. A large proportion of the funding was going towards the home itself, which put off most commercial lenders. Also, the existing business alone didn’t generate enough income to meet most lenders’ debt service requirements.
Solution
We reworked the business plan and found a lender prepared to look at the whole picture, including the future earning potential of the additional enterprises the client planned to build on the site.
Outcome
Full funding was secured. The client and his family have now purchased the farm and moved in, with the diversified business underway.
Client testimonial
“Thanks for everything and making our dream come true. The views are fantastic. It was well worth waiting for, and it’s everything we wanted.“
by Alison Jobson | Jun 24, 2026
A year ago, we helped finance the transformation of a Cornish family farm into one of the county’s most talked-about leisure venues. Twelve months on, we caught up with founder Will Eustice to hear how it’s gone.
From farmland to flagship venue
When Will Eustice first approached ASC, he had a bold idea to transform his family’s farm near Crantock on the North Cornish coast into something unique. His vision was to create a sports-led venue paired with a top food experience. He needed finance to build a 15-bay state-of-the-art Trackman-equipped golf range, a mini-golf course, and rustic feasting barns
It was an ambitious vision and a complex financing proposition.
Halwyn opened its doors on 16 June 2025. One year on, visitors have launched two million golf balls from its range, the feasting barns have served 10,000 covers, and the venue has earned a 4.7-star rating across more than 70 Google reviews. And, it’s not just its visitors who recognise Halwyn as a destination experience. It’s been shortlisted for Indoor Golf Venue of the Year at the Golf Course Awards 2025, and named a finalist in the Best Newcomer category at the Trencherman’s Awards 2026, widely regarded as the South West’s most prestigious hospitality awards.
Not bad for a first year. Especially one without any hospitality experience to fall back on.
A complex finance situation
Halwyn presented an unusual financing challenge. Will needed £600,000 to fund the build, yet securing a development loan for a start-up with no trading history in the hospitality sector, operating a concept that didn’t fit neatly into any established category, wasn’t going to be easy. It was simultaneously a leisure development, a food-and-beverage operation, and a new concept in experiential hospitality. Most traditional lenders weren’t quite sure what to make of it.
Our job was to find one that did.
Our local expert, Conrad Robins, identified a lender willing to take a merit-based approach. He targeted one that looked at the substance of the project and the strength of Will’s background as a professional quantity surveyor, rather than simply applying a standard risk assessment. The lender was sufficiently convinced that it didn’t request a formal valuation, and we secured a two-year facility drawn down in stages as the build progressed.
More than a venue
What’s perhaps most striking about Halwyn’s first year isn’t the numbers, but what the venue has become. Will set out to create a social community, and he has. Halwyn now hosts a monthly farmers’ market, has screened documentary films for the local community, and has a programme of events planned through the winter to keep the momentum going year-round. All food is locally sourced and handmade, and at peak season, a team of 20 keeps the venue running smoothly.
The challenge Will identified early on, namely, convincing people that exceptional food and a social sporting experience could genuinely coexist, appears to have been met
“With the support of ASC and our amazing team, we’ve built something people want to come back to,” says Will. “The plan now is to keep making it better.”
Have an unconventional project? Let’s talk.
Halwyn is a good example of what’s possible when financing is approached creatively. Some financing requirements can pose real obstacles with mainstream lenders, but that doesn’t mean the funding isn’t available.
If you have a project that doesn’t fit the standard mould, our network of local finance experts is well placed to help. We’ll find the right lender for your circumstances, not just the most obvious one.
Find your local ASC expert here.
by Alison Jobson | May 21, 2026
Client: The Aussie Smoker, award-winning BBQ catering company
Facility: £125,000 unsecured business loan
Purpose: Acquisition of new leasehold premises to secure the business’s future and enable growth
Client background
The Aussie Smoker is the brainchild of Adam, a Perth-born pitmaster who brought his family’s love of BBQs to Cornwall. It began as a catering operation from Adam’s driveway and has since grown into one of Cornwall’s most-loved food experiences, earning recognition as Best Alternative Caterer at the South West Wedding Awards for two consecutive years.
Having survived Covid and 17 postponed wedding catering jobs, The Aussie Smoker moved off the driveway and expanded into a shipping container on a rented plot of land. As demand grew, so did the number of rented shipping containers, until news arrived that the land was being redeveloped. Adam faced two choices – downsize or find new premises to push the business forward.
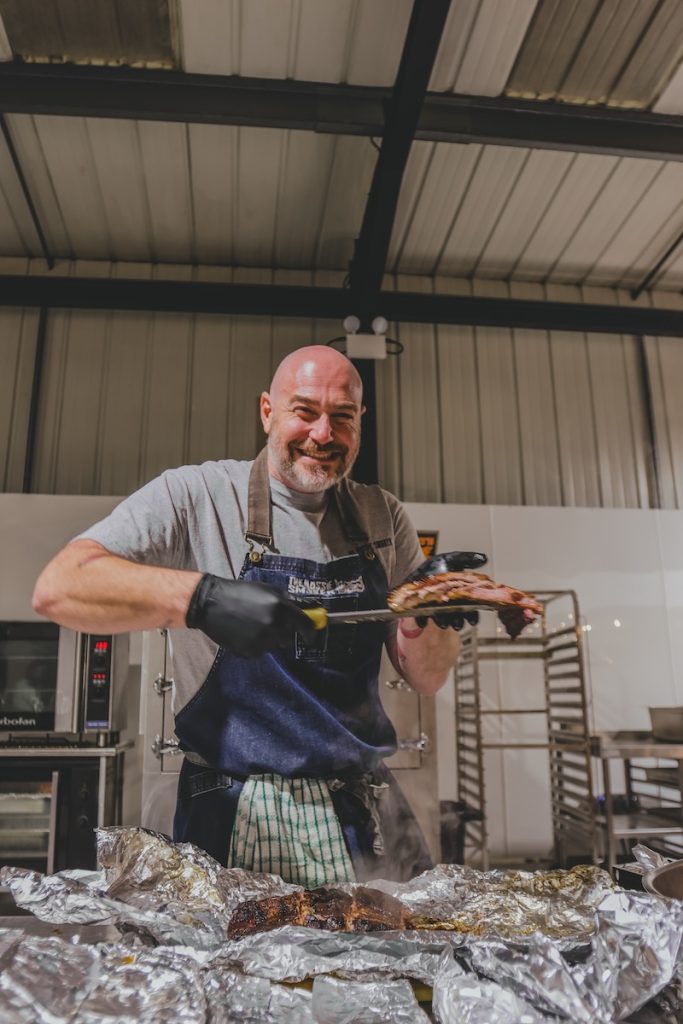
Adam, The Aussie Smoker
Challenge
Adam found a promising leasehold site that could take the business to a completely new level. However, he didn’t have the capital to secure the lease and fit out the new premises. He approached two commercial finance brokers, and both came back with the discouraging news that he could realistically expect to raise only £20,000 to £30,000, a significant shortfall. A recommendation brought him to ASC.
Unsecured business lending at this level presents genuine challenges. Lenders view shorter-term loans as higher risk, and securing a significant sum without asset security requires a compelling case. When we approached the market, the initial bank response was a maximum of £100,000, an uplift of £70,000 on previous brokers, but still left a £25,000 shortfall.
Solution
Rather than accepting the initial offer, we worked with the lender to present a stronger picture of the business. That meant providing a detailed view of Adam’s cash position, the business’s profitability, and, critically, the significant growth potential unlocked by the new site.
Comfortably persuaded, the lender increased their offer to the full £125,000.
Outcome
With the finance in place, The Aussie Smoker secured its new home and the impact has been transformational.
Where once there was a single service offering, there are now multiple revenue streams, including a walk-in lunch service, venue hire for weddings and private events with bespoke catering packages, BBQ masterclasses, and a growing range of frozen BBQ products. The business has the capacity to recruit more staff and the infrastructure to support the kind of growth that simply wasn’t possible before.
Adam’s vision of making people smile through food every day now has the permanent home it has always deserved.
Client testimonial
“ASC were incredibly professional, personal and gave us a lot of confidence in what we’re doing. They truly believed in us and didn’t try to finance something they didn’t trust had merit. The team were amazing. We wouldn’t be here without them.” – Adam, Founder, The Aussie Smoker
by create | Feb 9, 2026
Client: Property development company
Facility: £330,000 development finance
Purpose: Fund the early-stage build costs of a residential development
Client background: A new development company with a strategic opportunity
Our client is an established property developer with a newly incorporated development company. Having purchased two adjacent plots in a prime Edinburgh location and secured planning permission for two semi-detached houses on one of them, our client was seeking funding for the build costs.
The financing challenge: Development finance for an early-stage build
The development required £330,000 to cover the build costs, loan interest, and fees. With the plots valued at £200,000 and a projected gross development value (GDV) of £600,000 for the completed properties, the loan-to-value was 55% of GDV, a conservative ratio that would appeal to lenders.
However, several factors added complexity:
1. New company with limited trading history
Our client’s development company was newly incorporated, so it had minimal trading history. Although the client personally had extensive property experience, lenders often prefer established companies with proven track records.
2. Retained interest requirement
The client requested 12 months of retained interest, with the monthly interest rolled into the loan rather than paid from their own funds. This increases lender risk, as there is no cash flow during the build period to demonstrate that the loan can be serviced.
3. Early-stage project
Although planning permission had been secured for one plot and was pending for the second, and groundwork had been completed, the build hadn’t commenced. Some lenders prefer to finance projects at later stages, when construction risk is reduced.
4. Exit dependent on property sales
The repayment strategy relied solely on selling the completed properties. In a slower market, this could lengthen the loan term and increase lender exposure.
Solution: Securing the funding by mitigating perceived risk
Despite the challenges, the fundamentals were strong, so our strategic approach focused on emphasising them:
1. Promoting the developer’s broader experience and financial strength
Although the development company was new, the individual behind it had substantial property experience and a £2 million portfolio generating nearly £100,000 in annual rental income. We emphasised this track record to reassure lenders that they were backing an experienced developer, not a first-time builder.
We also highlighted the client’s personal residential property as additional evidence of financial stability.
2. Emphasising location and market demand
The plots’ proximity to the Royal Infirmary of Edinburgh was a key selling point. We provided market context showing strong sales growth in the area, supported by guidance from the project architect and local estate agents, who confirmed that valuations were realistic at £300,000 per property.
3. Demonstrating project readiness and straightforward execution
The groundwork had already been completed, planning permission was secured (with the second application expected imminently), and the build itself was straightforward. We positioned it as a low-risk, executable project with clear timelines.
4. Conservative LTV and strong security
At 55% of GDV, the loan-to-value was conservative, providing a significant equity cushion for the lender. We offered a 1st charge over the first plot and demonstrated that even if the market softened slightly, the lender’s position would remain secure.
We approached specialist development finance lenders we knew would recognise that retained interest is standard for projects with clear exit strategies.
Outcome: Full build financing
By presenting the full context, we secured £330,000 in development finance to enable the build to proceed. With 12 months of retained interest, the client could focus entirely on delivering a quality build without the pressure of monthly interest payments during construction.

by create | Feb 9, 2026
Client: Private equity professional
Facility: £525,000 business loan
Purpose: Leasehold children’s nursery acquisition
Background: Private equity professional seeks entry into childcare market
Our client was seeking finance to acquire an established children’s nursery business in Perth, Scotland, as the first step in a buy-and-build strategy. The initial acquisition would provide a strong platform business, with the intention of improving operational performance and then expanding the group by buying additional nurseries over time.
With a strong team experienced in private equity, nursery operations and people management, our client had identified a well-run nursery operator in Perth with solid fundamentals and clear scope for operational improvement, making it an ideal foundation for future growth.
The financing challenge: A complex deal structure
The purchase price was £750,000 with an intricate payment structure:
- £525,000 required upfront (the loan amount we needed to secure)
- £95,000 cash injection from the buyer
- £130,000 deferred payment over 12 months (demonstrating seller confidence)
Loan serviceability was strong, with confirmed occupancy several months ahead and planned price increases. However, the security was a challenge because it was a leasehold purchase. Although there was an option to purchase the freehold within three years, we needed to find a lender comfortable with leasehold security on a £525,000 commercial loan.
Solution: Matching the right lender to the acquisition opportunity
The leasehold security, together with the buy-and-build ambitions and the deferred payment structure, created complexity that is off-putting to many lenders.
We specifically approached lenders we know understand ‘buy-and-build strategies’ and have an appetite for leasehold commercial properties, provided the underlying business fundamentals are strong. By framing this as the first step in a regional consolidation play (with further nursery acquisitions planned), we positioned our client as a growth-oriented borrower who would bring repeat business.
Our approach focused on three key angles:
1. Highlighting the quality of the asset
We highlighted the nursery’s strengths and demonstrated that it was a stable, profitable business with growth potential. We also positioned the deal within broader sector trends, underscoring healthy future demand.
2. Emphasising management continuity
With all existing staff, including management, remaining post-acquisition, we emphasised that operational risk during the transition had been eliminated.
3. Demonstrating the borrower’s strategic capability
We presented our client’s comprehensive business plan, covering sector research, market analysis, and future acquisition targets, thereby demonstrating the depth of their preparation.
The outcome: Acquisition finance realised
We secured £525,000 in funding at competitive rates, enabling the acquisition to proceed on schedule. Our client is now well placed to execute their buy-and-build strategy, with this acquisition serving as a platform for future growth throughout Eastern Scotland.
